

Headlines:
- Gas and Electricity Wholesale prices are higher
- EU Gas Storage levels remain high at 78% full
- Large numbers of LNG deliveries continue to arrive in Europe
Energy Overview
As of the 3rd of July, Gas and Electricity Year Ahead Wholesale costs were higher, when compared to last month’s report.
The Oil price continues to have a lack of clear direction, as global economic data appears to show slow growth which adds downward pressure. OPEC+ members have brought in production cuts to stimulate the price, to support their economies and fund projects to diversify away from Oil’s income. It is currently $75, having fallen as low as $72 and as high as $77 in June.
EU Gas Storage levels are a healthy 78% full compared to 70% last month. This would suggest that the target of 90% by November can be achieved or exceeded and gives confidence that there will be sufficient Gas to supply a “normal” winter demand. LNG deliveries to the UK have reduced from recent highs but continue to head to Europe.
Electricity prices are following Gas, as it is the main source of generation. We do have a growing diversity of supplies, which includes renewables and connections to the continent, but they are not yet able to match the scale and reliability of Gas generation.
The Met Office forecast for July suggests temperatures are likely to be in the region of seasonal norm.
What does this mean for me?
The Energy Bills Discount Scheme (EBDS) replaced the Energy Bill Relief Scheme (EBRS) on the 1st of April 2023. It is designed to give all non-domestic customers, including the voluntary sector (such as charities) and the public sector (such as schools and hospitals) access to a phased in maximum discount when the customer’s wholesale cost exceeds the defined thresholds. This lasts for 12 months until 31st of March 2024 and applies to contracts that were put in place on or after 1st of December 2021 and non-contracted arrangements. As with the EBRS, energy suppliers will automatically apply these standard discounts. Although the levels of assistance are less generous, the price of Gas and Electricity is considerably lower than 2022. Those companies that are classed as Energy and Trade Intensive Industries (ETII) and Heat Networks, will receive a more attractive discount once applied for. Please see our Blog for more details.
Customers may have started to see higher Standing Charges on their Electricity invoices from 1st of April 2023. There have been changes to the way some industry charges are calculated, under the Targeted Charging Review. This move is part of an attempt to recover more Electricity costs, such as Transmission and Balancing, through fixed fees. In theory this should give both the customer and the industry a more accurate way of managing finances.
Indigo Swan are working closely with energy suppliers to help all our customers understand and manage these changes.
Please contact us on 0333 320 0475 to discuss options or to get a latest update.
Gas market overview
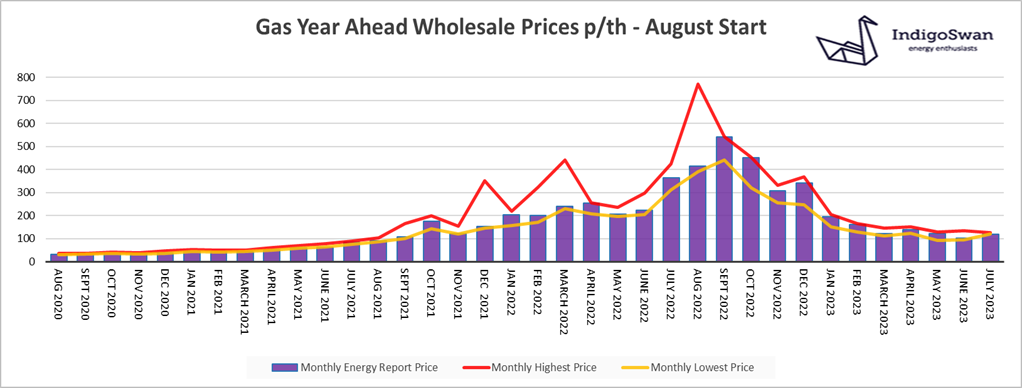
On the 3rd of July, the Gas Year Ahead Wholesale cost was 119.67p/th, up from 102.27p/th in last month’s report and 67% less than 2022.
Gas prices had been showing a slow downward trend since the start of the year, reaching 98p/th in early June for a twelve-month contract starting in August. The announcements that the Nyhamna Gas processing plant had extended its outage until the 15th of July 2023 due to an issue with the cooling system and that the Groningen Gas field will close by the 1st of October, earlier than expected, pushed prices higher. Last winter we avoided even more dramatic price spikes and the need for enforced Gas restrictions, due to the mild temperatures and consumers reducing demand to avoid some of the impact of higher costs.
Large quantities of LNG are still being delivered to Europe to help offset the reductions from Russia. Less LNG shipments are coming to the UK for Export to the continent as the likes of Germany now have their own facilities. EU Gas Storage is making good progress to reach the target of 90% full by November, currently at 78%. The supply position is more positive than last year, however, if there is an extended period of extreme cold or additional supply disruptions, there remains the possibility of some price volatility.
Energy suppliers are now offering a wider range of contracts so we would advise discussing your options for contracts ending in 2023 or early 2024 with Indigo Swan, for both one and two years.
Let us know if you would like us to research your options for 12, 24 and 36 month contracts.
Electricity market overview
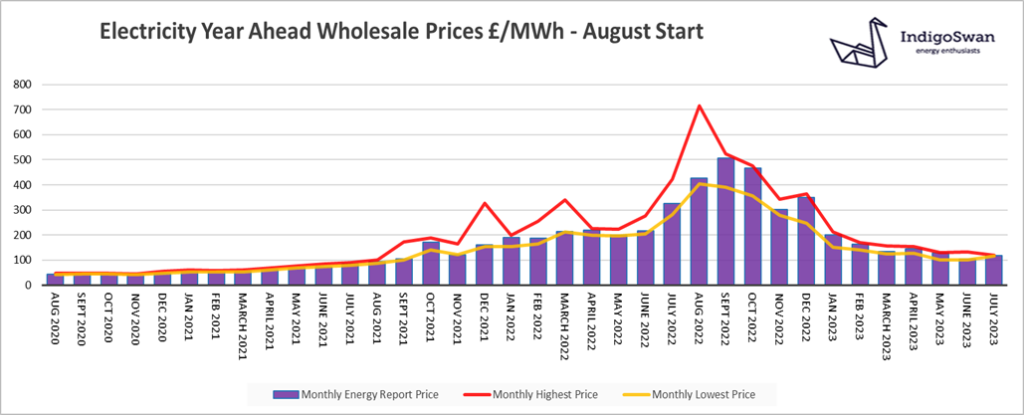
On the 3rd of July, the Electricity Year Ahead Wholesale cost was £118.00/MWh, up from £106.21/MWh in last month’s report and 64% less than 2022.
The high temperatures in June placed an additional demand on supplies for air conditioning. Wind’s contribution was once again low at just 16% of generation and Imports from Europe were also lower than May at 14%. This did mean that Coal had to be used although at just 0.35% and would most likely have been during those peak periods of demand.
Although an accurate figure cannot be obtained for Solar, there are growing numbers of both domestic and commercial projects, so it would be reasonable to assume Solar exceeded the 9% estimate for June.
The National Grid has mechanisms in place to help avoid power shortages and has taken additional steps to secure generation on demand. These measures do come at a cost premium, in the form of higher third-party charges within bills, but provide an element of stability to prices which otherwise may react even more dramatically. Their early winter lookout report which is based on the current understanding of supply and demand, forecasts we should have enough Electricity by continuing to use some Coal and the Demand Flexibility Service.
Let us know if you would like us to research your options for one and two years, for contracts ending in 2023 or early 2024.
Let us know if you would like us to research your options for 12, 24 and 36 month contracts.
If you enjoyed reading this blog why not try one of our others: