

Headlines
- Gas and Electricity Wholesale prices remain elevated as winter delivery begins.
- Hopes of a breakthrough in Middle East negotiations continue, but supply risks remain firmly in place.
- European Gas Storage has improved to around 71% full, but remains significantly below historical levels for this time of year.
Energy Overview
As of the 30th of September, Gas and Electricity Year Ahead Wholesale costs remained considerably higher than historic norms as the market entered the Winter 2026 delivery period. Front-month Gas opened October trading around 184p/th, while Winter Power contracts remained above £150/MWh.
For businesses preparing budgets and financial forecasts for 2027, energy markets continue to be shaped by geopolitics rather than traditional supply and demand fundamentals. Developments in the Middle East have dominated trading sentiment throughout September, with ongoing discussions between the US and Iran offering occasional optimism but little certainty. The market remains highly sensitive to any news relating to the Strait of Hormuz, a critical route for global LNG shipments.
While some LNG cargoes have resumed movement through the region, restrictions remain and traders continue to apply a risk premium to gas markets. As a result, businesses approaching contract renewal face a very different landscape to the one seen just twelve months ago.
A key concern remains European Gas Storage. Although inventories have increased from earlier lows, storage levels remain the weakest seen at this stage of the injection season, sitting well below both last year’s figures and the five-year average. With colder weather forecasts emerging across Europe, the market will be paying close attention to storage withdrawals during the coming weeks.
For organisations with energy contracts due to expire over the next six to twelve months, now is a sensible time to review procurement strategies. Waiting for markets to settle may feel tempting, but volatility can move quickly and opportunities often appear with little notice.
Other Industry Costs
Whilst Wholesale energy prices continue to dominate headlines, non-commodity costs remain a growing part of the overall bill.
Network charges, balancing costs and policy-related levies continue to add pressure to budgets, particularly for larger energy users. For many businesses, understanding when and how energy is consumed is becoming just as important as the price paid for the energy itself.
Organisations with Half-Hourly electricity supplies should continue reviewing demand profiles, capacity requirements and opportunities to improve efficiency. These measures can help offset some of the increases being seen elsewhere across the energy landscape.
Gas Market Overview
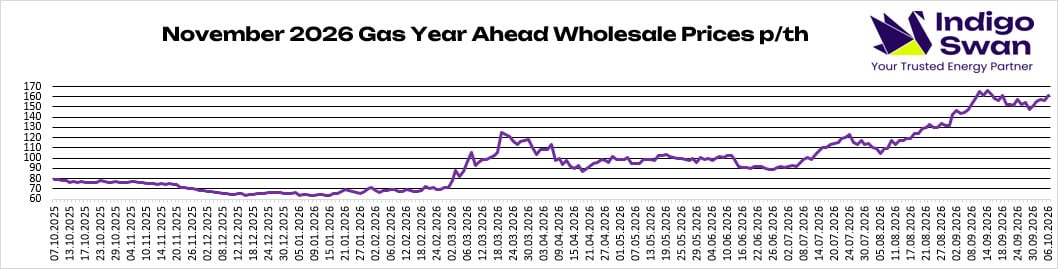
On the 30th of September, the Gas Year Ahead Wholesale cost remained significantly above levels seen throughout much of 2025, reflecting continued concerns around global supply security.
The market continues to focus on three key themes:
- Ongoing uncertainty surrounding the Middle East conflict.
- Reduced confidence in global LNG availability.
- Lower-than-normal European Gas Storage levels heading into winter.
Norwegian gas flows have improved following the resolution of an unplanned outage at the Troll processing facilities, helping to provide some stability to European supply. However, planned maintenance remains in place across several key assets, limiting the extent of any downward price pressure.
Looking ahead, weather will become increasingly important. Forecasts suggest heating demand across Europe could begin rising sharply during October as temperatures return closer to seasonal norms. Strong early winter demand would place additional pressure on storage levels and could increase market volatility.
We would encourage any customer with contracts ending in the coming months to speak with us about their options. Having a clear strategy in place can provide greater certainty in what remains a highly reactive market.
Electricity Market Overview
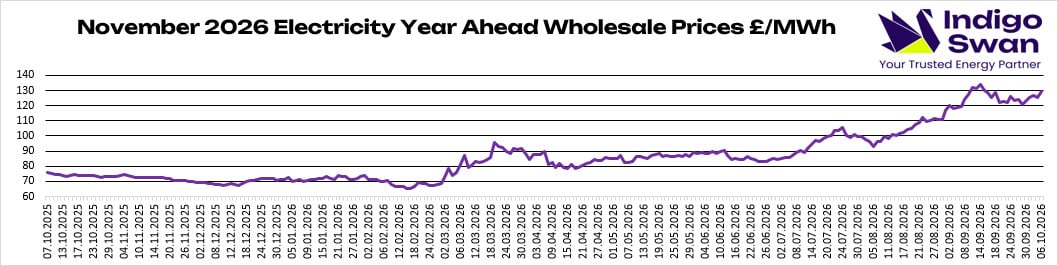
Electricity markets continue to take their lead from Gas.
Gas-fired generation remains a crucial part of the UK’s electricity mix and, because it is often the marginal fuel source, movements in Gas typically translate directly into Power prices. As Gas markets strengthened during September, Electricity contracts followed a similar trajectory.
Generation patterns also shifted throughout the month. During the week commencing 21st September, Wind generation contributed 39% of UK electricity production, reducing reliance on Gas. By the following week, lower Wind output saw Gas generation rise to 29%, highlighting how quickly market dynamics can change.
The UK also continues to rely on imported power via interconnectors, with imports contributing between 10% and 13% of supply during recent weeks. This means continental market conditions continue to influence domestic Electricity pricing.
For businesses, the key message remains unchanged: uncertainty creates risk, but it also creates opportunity. Organisations that engage early with their procurement strategy are often best placed to take advantage of market movements when they occur.
Closing Thought
Budget season is now underway for many businesses. In an energy market driven by global events, contract decisions are no longer just a procurement exercise.
They’re a risk management decision.
The organisations that understand their options before they need to act will be in the strongest position as we move deeper into winter.
Get in Touch
The final quarter of the year is when many organisations turn their attention to budgets, forecasts and planning for the year ahead. Energy should be part of that conversation.
Reviewing contract end dates, understanding your procurement options and assessing potential risks now can help avoid rushed decisions later.
If you’d like support reviewing your position, let’s have a conversation.